Short answer
Sometimes. Homeowners insurance tends to look at the event behind a smell, not the smell itself. Odor tied to a sudden covered loss, such as a house fire or a burst pipe, may be considered as part of that claim. Odor from gradual causes like pets, smoking, or long-term neglect is often excluded. Only your carrier can decide, so ask for its position in writing.
Insurers look at the cause, not the smell
A homeowners policy is built around perils, meaning the events that cause damage. Odor is almost never named as a peril on its own. It is treated as a symptom of something else that happened in your home.
That is why two households with equally strong odors can get very different answers. One smell came from a kitchen fire last week. The other built up over years of indoor smoking. The fire is a sudden event the policy was written to address. The smoking is a slow condition most policies exclude.
When you call your carrier, lead with the event, the date, and what you observed. Saying the house smells bad gives the adjuster nothing to evaluate. Saying a pipe under the bathroom failed on a specific night and the water sat under the vanity gives them a covered-peril question they can actually answer.
Which odor situations are more likely to be considered?
No list can predict your outcome, because forms, endorsements, and exclusions differ from policy to policy. Still, some odor sources tend to be linked to events that carriers commonly review.
Smoke is the clearest example. The US Fire Administration estimates 343,000 residential building fires in 2024, with cooking the leading cause at 46.7% of incidents. When a fire or smoke event is part of an open claim, deodorization of walls, contents, and ductwork is often discussed as part of restoring the home.
- Smoke and soot odor following a fire, including a small contained kitchen fire
- Odor from sudden water damage, such as a supply line failure, if the water loss itself is reviewed
- Decomposition odor after an unattended death, which some carriers evaluate under specific coverage parts
- Odor from a vandalism or break-in event where material was damaged or left behind
- Sewage odor after a backup, but only if your policy carries a water backup endorsement
Odor problems that are usually excluded
Carriers generally treat gradual, preventable, or maintenance-related problems as the homeowner's responsibility. Many odor complaints fall into that group, which surprises people who assumed a smell alone would qualify.
Pet urine is the most common frustration. Damage from animals you own is frequently excluded, and urine that has soaked into pad and subfloor over months looks like wear rather than a sudden loss. Cigarette and cannabis residue fall in the same category. So do musty smells from long-term humidity, a slow roof leak nobody fixed, or a crawlspace that stayed damp for years.
Sewage is a special case worth checking now, before anything happens. Many standard forms exclude water that backs up through drains or a sump unless you added a specific endorsement. Look at your declarations page today and see whether that line appears. If it does not, ask your agent what it would cost to add.
Exclusion does not mean you have no options. It means you should plan to pay directly, get competing quotes, and ask the provider to phase the work so the most important rooms come first.
A realistic claim, step by step (illustrative)
The case below is illustrative; Dana is a composite, not a real client. She returns from a two-week trip in August. A chest freezer in the garage failed while she was gone. The spoiled contents leaked across the slab and under a shared wall into the laundry room. The house smells strongly, and the drywall base in the laundry room is stained.
Dana photographs the freezer, the leak path, the stained wall, and the date on the circuit breaker log from her smart panel. She calls her carrier before throwing anything away and asks which coverage part the adjuster will evaluate. She asks whether she can remove spoiled food right away to stop the odor from spreading, and she writes down the name of the person who says yes.
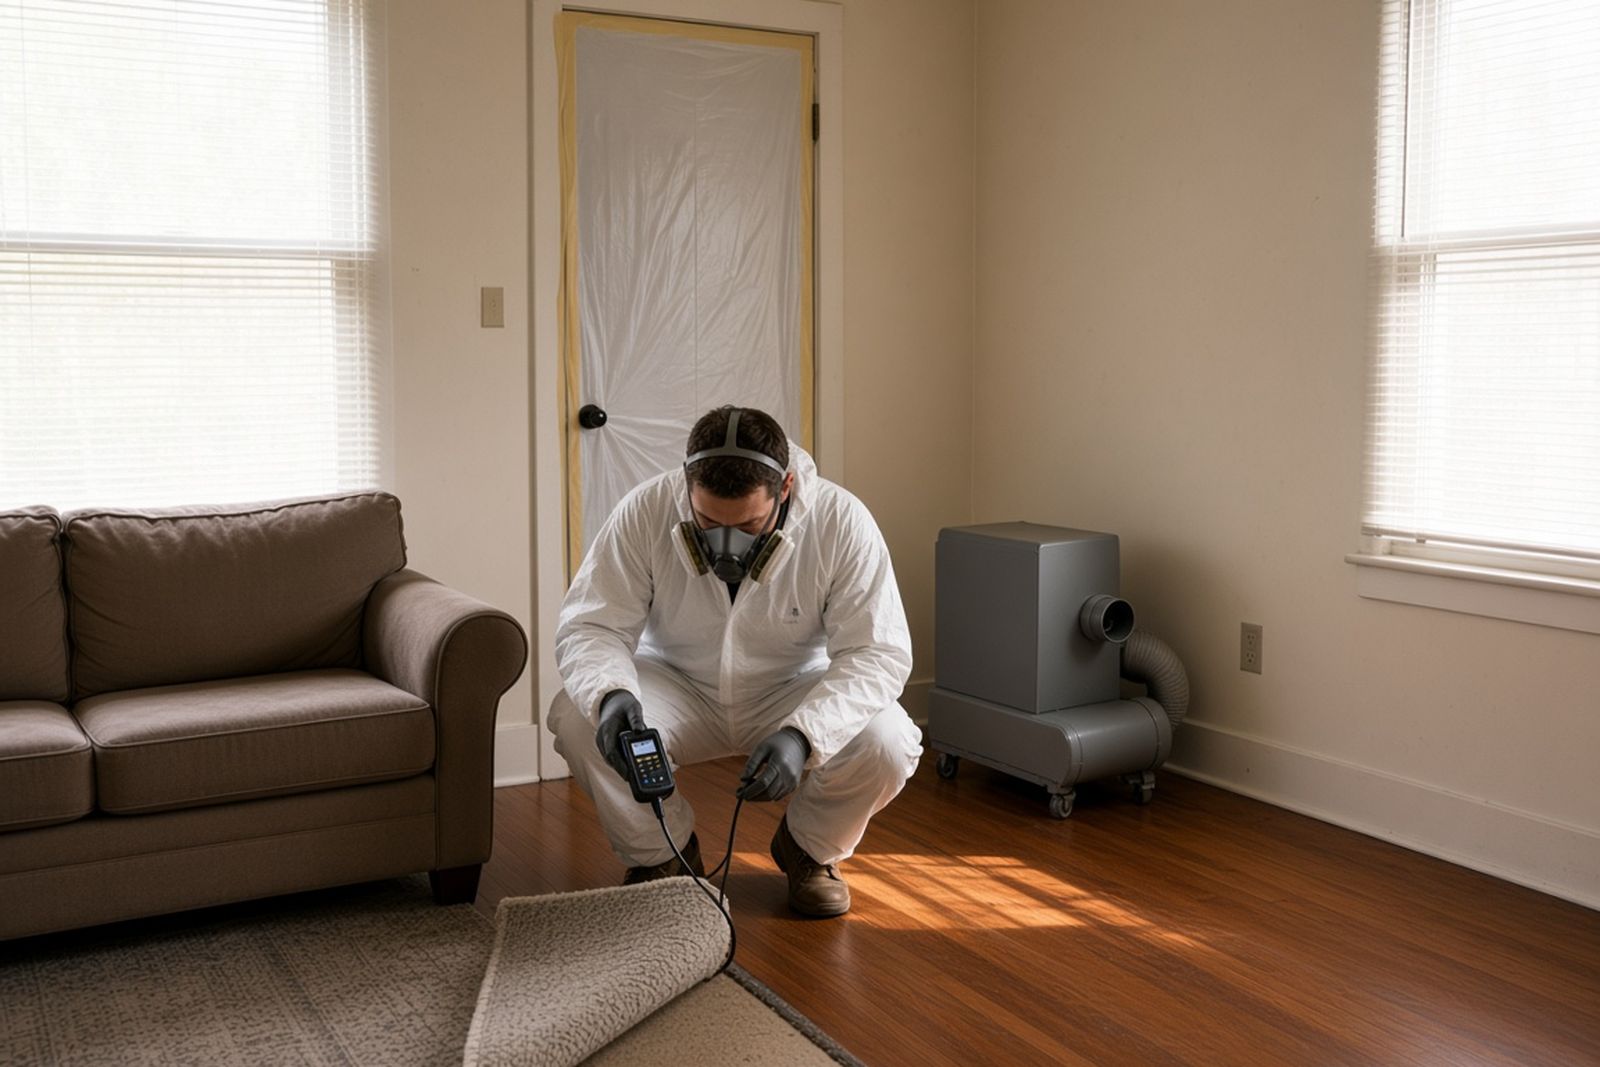
An odor remediation company inspects and writes a scope. The scope separates the source removal, the cut-out of wet drywall and baseboard, the sealing of the slab, and any air treatment afterward. The adjuster may treat some items differently than others. Food spoilage coverage, for instance, is often a separate limit, if it exists at all. Dana does not assume anything is paid until she has the carrier's position in writing.
Documenting an odor for an adjuster
Smell cannot be photographed, so you have to document what causes it. Adjusters respond to evidence of the source, the spread, and the damage to materials.
Start before anything is cleaned or discarded, unless doing so would put someone at risk. If a room is unsafe, leave and let professionals handle the documentation.
- Wide photos of each affected room, then close-ups of stains, residue, and damaged materials
- Photos of the suspected source, such as a failed appliance, a burned area, or a backed-up drain
- A written timeline with dates, when you first noticed the smell, and who was in the home
- Receipts for any emergency steps, including fans, dehumidifiers, or temporary lodging
- Incident numbers from the fire department, police, or medical examiner if they responded
- The remediation company's written scope, listing each area and each material separately
Can a remediation company guarantee that my insurer will pay?
No. Be cautious of anyone who says otherwise. A remediation provider can inspect, document, and write a clear estimate. It cannot bind your carrier, and it cannot promise what the adjuster will approve.
Some providers offer to bill the carrier directly. That arrangement can be convenient, but read what you are signing. A direction-to-pay or assignment form may affect who controls parts of the claim and who is responsible if the carrier denies a line item. Ask the provider to explain the form in plain language and to put its payment expectations in writing.
Also watch for scopes that lean heavily on air treatment without addressing the source. An adjuster reviewing a scope may ask why a machine is on the invoice if the contaminated pad or drywall stayed in place.
When a tenant or previous owner caused the smell
Rental properties and recent purchases add another layer. A landlord's policy is usually a dwelling or landlord form, not an HO-3, and it may treat tenant-caused damage differently. Smoking, pet damage, and neglect are often handled through the lease and security deposit rather than insurance.
If you bought a home and discovered a hidden odor after closing, your first conversation may be with your real estate agent or an attorney rather than your insurer. Ask them what seller disclosure obligations applied to your purchase and what records would help.
Either way, keep the same records: photographs, dates, the source, and a written scope. They are useful whether the path forward is a claim, a deposit deduction, or a negotiation with a seller.
Landlords turning over a unit should also think about timing. A smell that seems faint in an empty, cool apartment can return strongly once a new tenant moves in, runs the heat, and closes the windows. Getting the source addressed before listing the unit protects you from a complaint that arrives weeks after the lease is signed.
Questions for your carrier before work starts
A short, specific list of questions keeps the conversation focused. Ask them on the phone, then follow up by email so you have a record of what was said.
If the carrier's answer is unclear, ask for a written coverage position before approving work that removes materials. Once drywall, carpet, or pad is gone, it is harder to show what the damage looked like.
- Which peril are you evaluating for this odor, and which coverage part might respond?
- Can emergency mitigation begin now, and is there a limit on what I can authorize without approval?
- Do you need to inspect before damaged materials are removed?
- What documentation do you need from the odor remediation company?
- Is there a separate limit for contents, food spoilage, or additional living expense?
- Will you pay the provider directly or reimburse me?
What if the claim is denied?
Ask for the denial in writing, with the specific policy language the carrier relied on. Read that language against your declarations page and any endorsements. Sometimes the issue is a missing document, not a true exclusion.
You may be able to request a reinspection, submit additional evidence, or use the appraisal or complaint processes available in your state. Rules vary by state and county; verify with the local authority, such as your state insurance department.
If you end up paying directly, you still have leverage. Get at least two written scopes, compare how each one addresses the source rather than only the air, and ask what verification step will show the odor is truly gone before the final invoice.